

The best business account in Singapore for most SMEs is two accounts, not one: a local bank current account for SGD, PayNow, GIRO and insured deposits, plus a multi-currency account such as Airwallex, Wise or Aspire for foreign currency and cards. Which ones depend on whether you trade locally, pay overseas suppliers, collect from marketplaces or need team cards. Every fee below was checked on the provider's Singapore page on 6 October 2026.
Part of The Gantry's automation guides. Updated October 2026.
General information on published fees, not financial advice. Fees change; confirm on the provider's page before applying.
I set up accounting and ERP for SMEs (I implement Odoo), so I judge accounts by one test: does the money land in the books without anyone typing it?
Quick verdict: the best business account in Singapore by provider
CIMB SME Account: best for a local-only business that wants no minimum balance.
OCBC Business Growth Account: best for a new company keeping at least S$1,000 in the bank.
DBS Business Multi-Currency Account: best for a business under 3 years old wanting 13 currencies at one bank.
UOB eBusiness Account: best for a business keeping S$5,000 or more and paying overseas by telegraphic transfer.
Maybank FlexiBiz Account: worth comparing if you bank with Maybank in Malaysia.
Airwallex: best for importers and online sellers collecting and paying in many currencies.
Wise Business: best for low, published conversion fees with a one-off set-up fee.
Aspire: best for a startup that wants free cards, spend limits and receipts synced to Xero.
Revolut Business: an option if your team already uses Revolut.
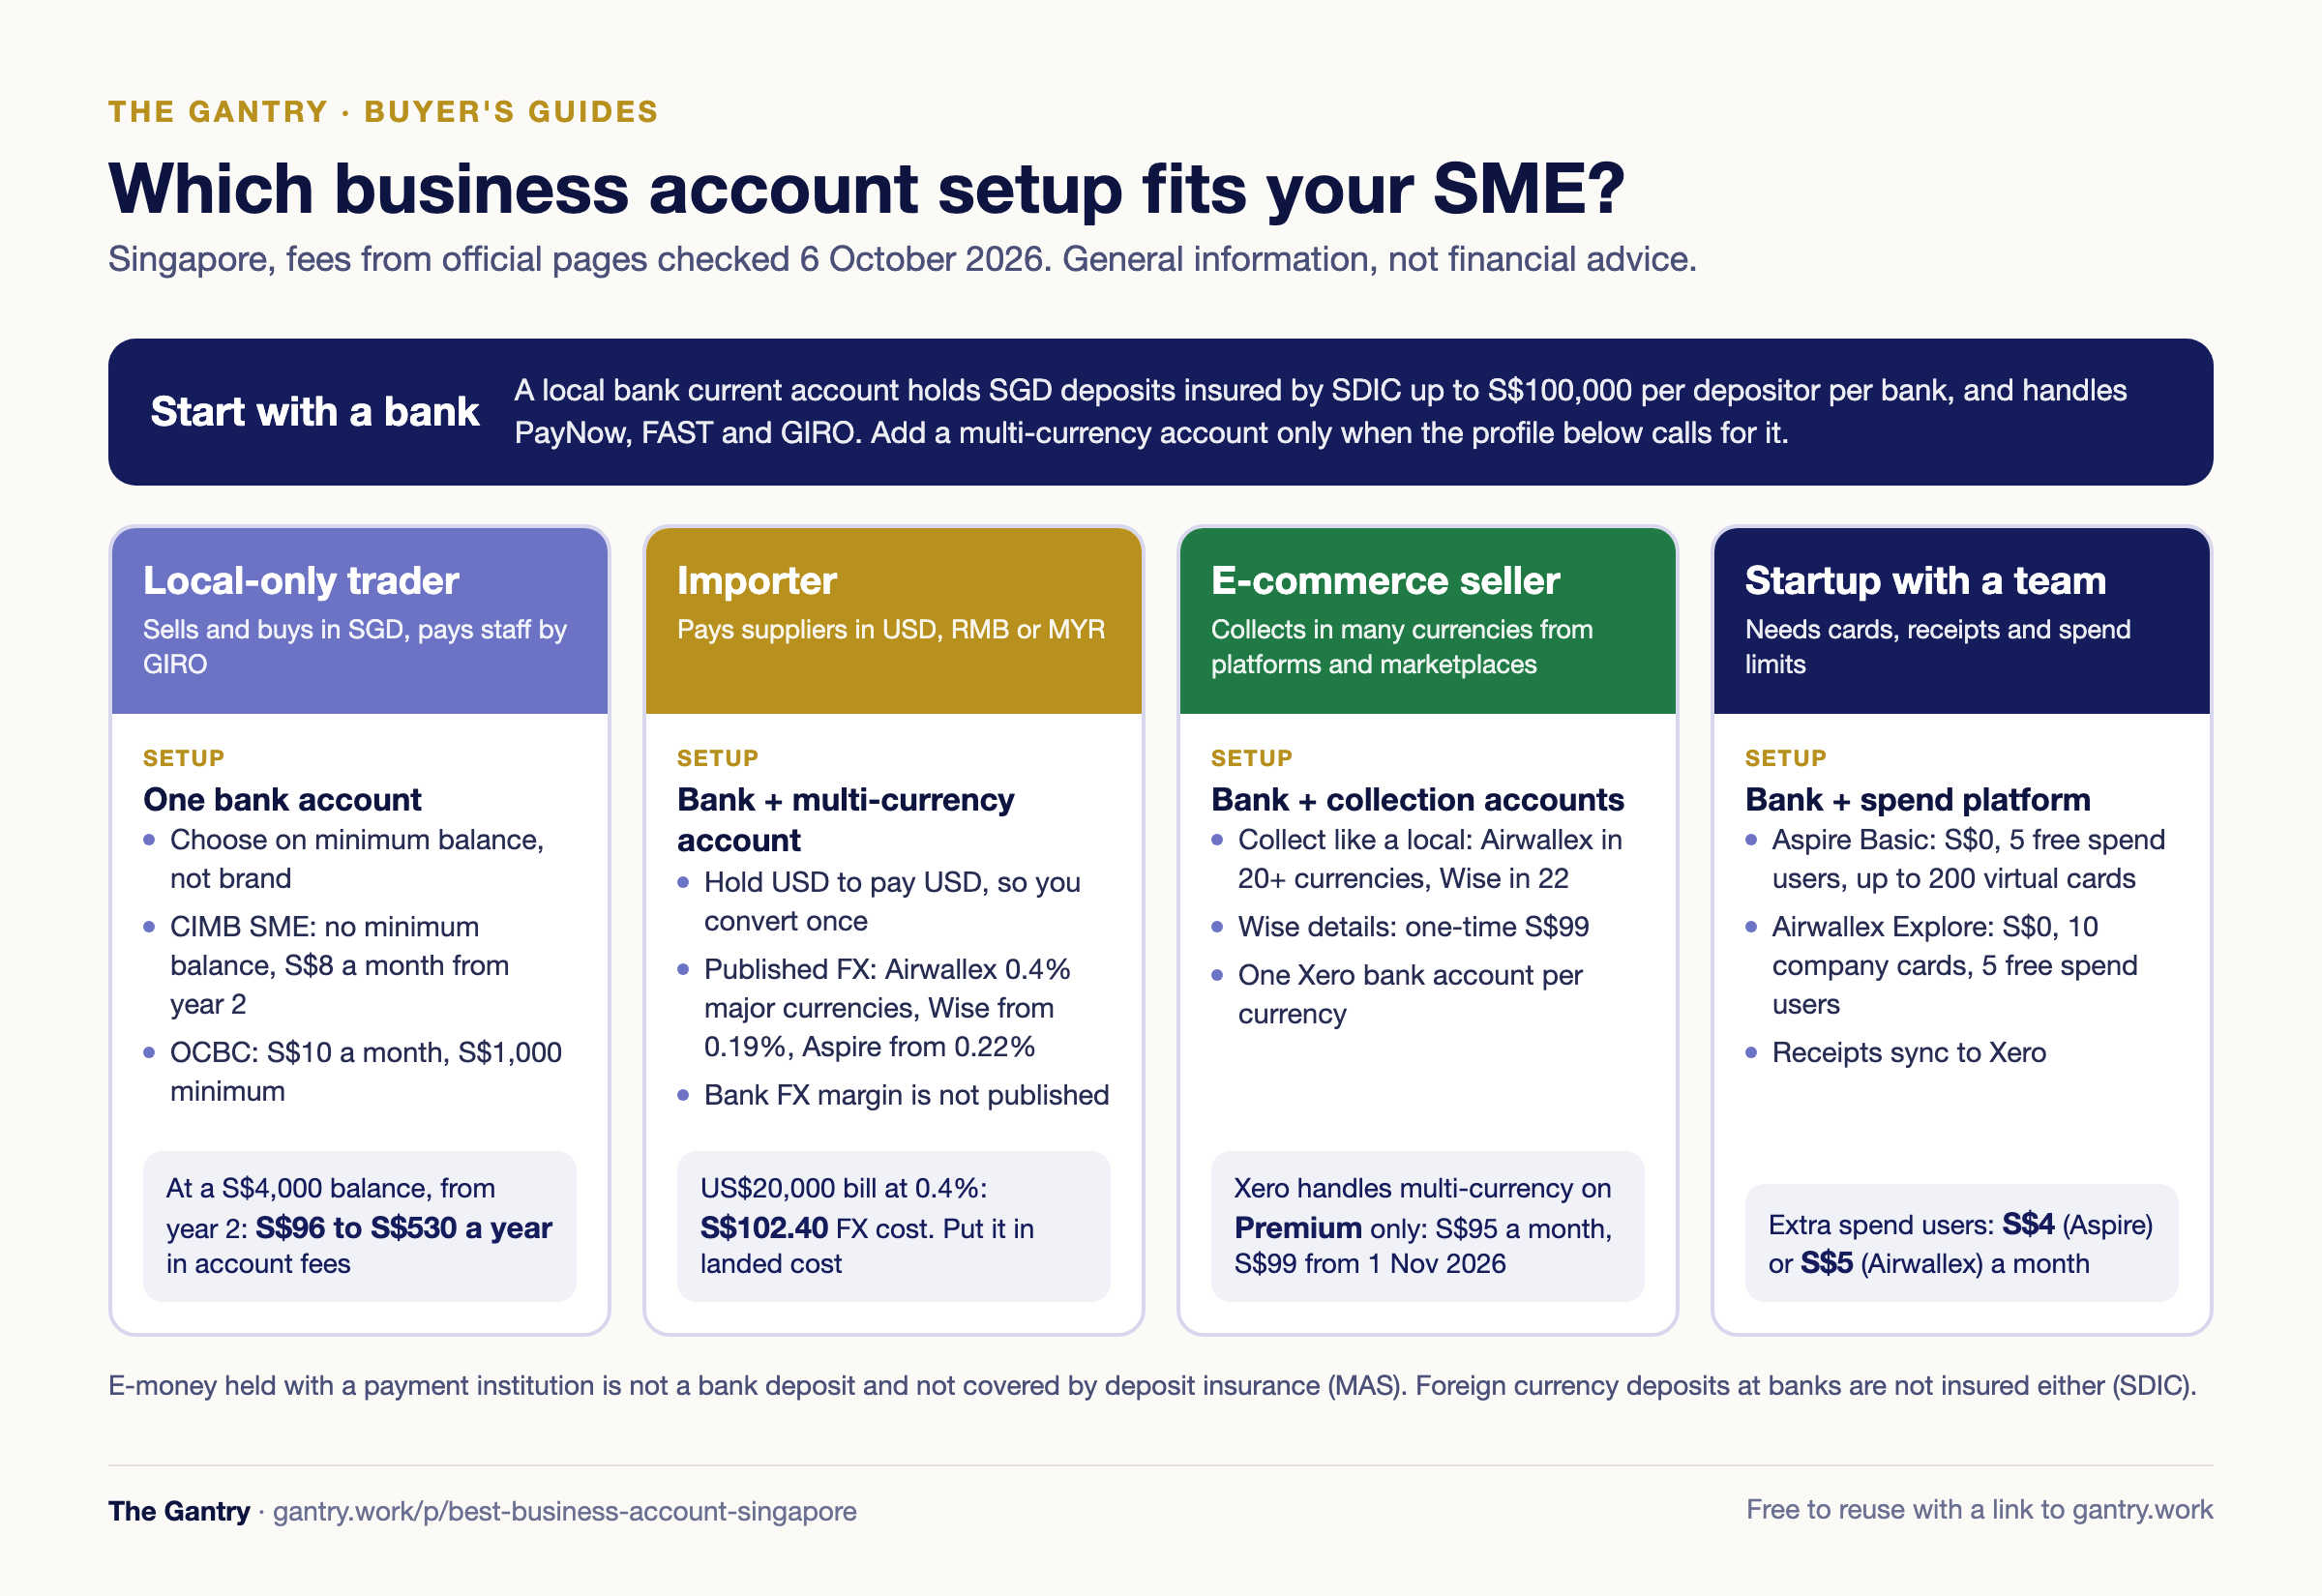
Which business account fits which kind of SME?
Match the setup to how your money moves.
Local-only trader (SGD in and out, GIRO payroll): one bank account, chosen on minimum balance.
Importer paying USD, RMB or MYR: bank plus a multi-currency account, so you hold USD and pay USD.
E-commerce seller collecting in many currencies: bank plus an account with local collection details abroad.
Startup with a team: bank plus a spend platform with per-card limits and receipt capture.
Traditional banks: fees and minimum balances (checked 6 October 2026)
Banks give you insured SGD deposits, cheques, GIRO, PayNow and a route to loans and trade finance.
The Singapore Deposit Insurance Corporation (SDIC) insures SGD deposits of non-bank depositors, companies and sole proprietorships included, up to S$100,000 per depositor per scheme member. Foreign currency deposits are not insured (SDIC).
DBS Business Multi-Currency Account
Best for: businesses under 3 years old (Starter Bundle) that want one account for SGD and foreign currency.
Price from: Starter Bundle S$10 a month, no monthly service charge. Standard account S$50 a year plus a S$40 monthly service charge, waived if your average daily balance is at least S$10,000. Fees include GST where applicable.
Strengths: 13 currencies including USD and CNH; unlimited free FAST and GIRO on the Starter Bundle, 50 a month otherwise; a debit card with no FX charges.
Limits: outward telegraphic transfer S$30 plus agent bank fees; no MYR.
Singapore notes: the set-up fee is S$0 only for fully locally owned businesses applying online.
OCBC Business Growth Account
Best for: new companies that can keep S$1,000 in the account.
Price from: S$10 a month, waived for the first 2 months; S$1,000 initial deposit; S$15 a month if the monthly average balance falls below S$1,000.
Strengths: 80 free FAST and 80 free GIRO a month; add the Multi-Currency Business Account (13 currencies, no minimum balance) and one S$10 fee covers both.
Limits: the multi-currency account does not include MYR.
Singapore notes: free Xero feeds, foreign currency accounts included.
UOB eBusiness Account
Best for: businesses that keep S$5,000 or more and pay overseas suppliers.
Price from: S$35 a year; S$1,000 initial deposit; S$15 a month if the average daily balance is under S$5,000, waived for the opening month and the next 11.
Strengths: rebates on up to 60 FAST or PayNow and 60 GIRO payments a month; online telegraphic transfers at a promotional S$15 until 31 December 2027, plus agent charges.
Limits: S$50 early closure fee within 12 months; foreign-incorporated companies pay a set-up fee of at least S$500.
Singapore notes: links to Xero, Info-Tech and AutoCount.
CIMB SME Account
Best for: local-only businesses that do not want to park cash to avoid fees.
Price from: S$0 a month in year one, then S$8. No minimum balance or fall-below fee; an initial deposit only at CIMB's discretion.
Strengths: unlimited free FAST, GIRO and payroll via BizChannel@CIMB; telegraphic transfers free for 12 months under a promotion ending 31 December 2026 (normally S$15); CIMB advertises its best SGD-MYR rate for B2B transfers on weekday mornings.
Limits: S$50 if you close within 6 months.
Singapore notes: suits frequent Malaysian supplier payments.
Maybank FlexiBiz Account
Best for: businesses already banking with Maybank in Malaysia.
Price from: no monthly fee, with a S$1,000 initial deposit and a S$10 monthly fee if the average daily balance falls below S$1,000 (FlexiBiz page, checked 6 October 2026).
Strengths: no account fee while you keep S$1,000 in it.
Limits: FAST transfers cost S$0.50 each, where several rivals include them free, and closing within 6 months costs S$50.
Singapore notes: Singapore dollar deposits are insured by SDIC up to S$100,000 per depositor per bank; foreign currency deposits are not.
Digital providers: Airwallex, Wise, Aspire and Revolut
Digital accounts are cheaper for foreign currency and better at cards, but the balance is e-money. MAS says e-money is not a bank deposit and is not protected by deposit insurance; major payment institutions must safeguard customer money instead (MAS FAQ).
Airwallex
Best for: importers and online sellers who collect and pay in several currencies.
Price from: Explore S$0; Grow S$79 a month; Accelerate from S$399 a month, in SGD excluding GST, per legal entity.
Strengths: collect and hold in 20+ currencies; free local transfers to 120+ countries; FX 0.4% above interbank for major currencies, 0.6% for others; Visa cards with no international transaction fees; Xero and QuickBooks feeds.
Limits: SWIFT transfers cost 20 to 35 each, currency not stated; Explore includes 10 company cards and 5 spend users, then S$5 per extra user a month; multi-conditional approvals and purchase orders need Grow.
Singapore notes: Airwallex (Singapore) Pte. Ltd. is a Major Payment Institution regulated by MAS (licence PS20200541). Official site.
Wise Business
Best for: businesses that want low, published conversion fees and no monthly fee.
Price from: a one-time S$99 set-up fee that covers every Wise Business feature, including account details to receive in 22 currencies.
Strengths: conversion from 0.19%, varying by currency; free domestic receipts in nine currencies including USD, EUR and GBP; Xero and QuickBooks connections.
Limits: USD wire and SWIFT receipts cost US$6.11 each; no local ATM withdrawals in Singapore.
Singapore notes: Wise Asia-Pacific Pte. Ltd. is listed by MAS as a Major Payment Institution.
Aspire
Best for: startups that want cards, budgets and expense claims without a monthly fee.
Price from: Basic S$0; Premium S$15 a month. No set-up fee and no minimum balance.
Strengths: accounts in SGD, USD, EUR, GBP, MYR, PHP, IDR and VND; FX from 0.22% on Basic and 0% on the first S$13,000 a month on Premium; up to 200 virtual cards and 1 physical card per user; 5 free spend users, then S$4 each a month.
Limits: the per-transfer fee for international payments is not shown on the pricing page (Premium includes 5 free a month, valued at up to US$75).
Singapore notes: Aspire FT Pte. Ltd. states it holds a temporary exemption from licensing under the Payment Services Act for account issuance, domestic transfers and e-money, with some cross-border transfers run by licensed partners. Read its disclosure.
Revolut Business
Best for: teams already comfortable with Revolut's app.
Price from: Basic from S$0 a month, Grow from S$15, Scale from S$84 (Singapore plan page, checked 6 October 2026).
Strengths: each plan includes a monthly allowance exchanged at the interbank rate: S$1,500 on Basic, S$13,000 on Grow, S$60,000 on Scale.
Limits: above the allowance a 0.6% exchange fee applies, and 1% outside market hours.
Singapore notes: Revolut Technologies Singapore Pte. Ltd. is listed by MAS as a Major Payment Institution.
What does foreign exchange really cost an importer?
On a US$20,000 supplier bill, published FX markups range from about S$49 to S$102; your bank's margin is the number you have to ask for.
A typical example, not a quote: a US$20,000 monthly invoice at an illustrative S$1.28 per US dollar is S$25,600.
Airwallex at 0.4%: S$25,600 × 0.004 = S$102.40.
Aspire Basic from 0.22%: S$25,600 × 0.0022 = S$56.32.
Wise from 0.19%: S$25,600 × 0.0019 = S$48.64. "From" means your currency pair may cost more.
Your bank: no FX margin is published on the account pages. Compare the rate on the day with mid-market; a 1% gap here is S$256.
Two habits matter more: hold USD receipts to pay USD suppliers, and put FX and bank charges into item cost through landed cost, or your margins look better than they are.
What does a local-only account cost a year?
At a S$4,000 average balance, account fees run from S$0 to S$530 a year from the second year, depending on the bank, before transfer charges.
Maybank FlexiBiz: S$0, since the balance stays above S$1,000; FAST transfers cost S$0.50 each, so 40 a month adds S$240 a year.
CIMB SME: S$8 × 12 = S$96.
OCBC Business Growth: S$10 × 12 = S$120, no fall-below fee above S$1,000.
DBS Starter Bundle (under 3 years old): S$10 × 12 = S$120.
UOB eBusiness: S$35 + (S$15 × 12) = S$215, once the 12-month waiver ends.
DBS standard account: S$50 + (S$40 × 12) = S$530, below the S$10,000 threshold.
Keep S$10,000 at DBS and its service charge disappears: your real balance decides the ranking.
What must a business account connect to?
It must feed your accounting system automatically, each currency to its own ledger bank account, or month-end becomes typing.
Banks: DBS links to Xero, QuickBooks, Info-Tech and Financio; OCBC feeds Xero daily; UOB links to Xero, Info-Tech and AutoCount. For other banks, Xero suggests checking under Accounting, Bank accounts, Add bank account.
Airwallex: bank feeds, expenses and bills sync with Xero and QuickBooks.
Wise: each Wise currency connects to its own Xero bank account.
Aspire: SGD, IDR and USD accounts sync to Xero every 3 hours, on Xero Business Edition only.
Two catches. Xero handles multiple currencies only on Premium, S$95 a month and S$99 from 1 November 2026 (Xero). And every extra account is another reconciliation. Choosing the books too? See AutoCount vs Xero vs Odoo; gateway payouts are covered in Stripe ASEAN reconciliation. Once receipts match automatically, the free AR Aging Report shows who really owes you.
Corporate cards in Singapore: which one gives you expense control?
For most SMEs, a multi-currency card with per-card limits and receipt capture gives more control than a corporate credit card.
Bank debit cards: DBS Business Advance+ has no FX charges; UOB advertises 0% FX fees overseas on its Business World Debit Card. Terms apply.
Airwallex: cards spend from held balances; employee cards and reimbursements are on the free plan.
Aspire: virtual cards per subscription, budgets and claims; a credit limit for eligible businesses.
Credit cards: a credit line, so expect the issuer to assess your company first.
Control comes from one card per vendor or person, a limit on each, and a rule: no receipt, card frozen. Otherwise cards just move the mess to month-end.
What documents do you need to open a business bank account in Singapore?
Expect an ACRA Business Profile, IDs for directors and signatories, the constitution, a board resolution and tax self-certifications.
UOB's private limited checklist: application form, ACRA Business Profile, NRIC or passport, proof of address for foreigners, FATCA and CRS forms, an account opening resolution and a certified constitution. DBS opens accounts online without documents if the company is fully owned by citizens or permanent residents and verifiable through Myinfo or ACRA.
A Business Profile costs S$5.50 on Bizfile and arrives within 15 minutes (ACRA). Since 27 March 2026, whoever files a registration, renewal or annual return gets a free copy in their Bizfile inbox for 60 days. Digital providers collect similar details online.
Common mistakes when choosing a business account
Using a personal account. Someone then sorts personal spending out of the ledger monthly.
Parking all your cash in e-money. Keep operating SGD at a bank, where SDIC cover applies.
Ignoring the fall-below fee. S$40 a month at DBS below S$10,000 is S$480 a year.
Opening accounts the books never see. Connect the feed on day one.
Best business account in Singapore: my recommendation
Open a bank account first: CIMB SME if your balance swings low, OCBC or the DBS Starter Bundle if you keep a few thousand, UOB or DBS standard only if you clear the fall-below threshold. Then add one digital account for what your bank does badly: Airwallex for many currencies, Wise for low conversion fees, Aspire for team cards. Both feeding the ledger.
Setting up accounts, cards and bank feeds so month-end closes itself? Bring your setup (banks, currencies, cards, accounting software) to a free 20-minute systems review. I will tell you what to connect and what to close.
Stuck on a step? Tell me where you're stuck and you'll get the fix, or a free 20-minute review if it's worth one.
Frequently asked questions
What is the best bank account for a small business in Singapore? The one whose minimum balance you can keep: CIMB SME has none, OCBC Business Growth S$1,000, UOB eBusiness S$5,000.
Can I open a business bank account in Singapore online? Yes. DBS and UOB open online via Myinfo for companies fully owned by citizens or permanent residents; others may need extra documents.
Are Airwallex and Wise accounts covered by SDIC? No. MAS says e-money is not a bank deposit and is not deposit-insured; major payment institutions must safeguard customer money instead.
What is the best multi-currency account in Singapore for business? Airwallex for collecting in many currencies, Wise for low published conversion fees, Aspire for MYR. DBS and OCBC hold 13 currencies but do not publish FX margins.
Corporate credit card or debit card for an SME? For control, a multi-currency card with per-card limits. A credit card makes sense when you need the credit line.
Related guides
Landed cost · Odoo vs Xero in Singapore · AutoCount vs Xero vs Odoo · Stripe ASEAN payment methods and reconciliation · Month-end shouldn't take three weeks
Sources
All checked 6 October 2026.
DBS Business Multi-Currency Account and DBS business account pricing: fees, service charge, currencies, FAST and GIRO allowance, debit card, accounting links.
DBS: opening a business bank account: online opening criteria.
OCBC Business Growth Account, OCBC Multi-Currency Business Account and OCBC Xero connection: fees, currencies, Xero feeds.
UOB eBusiness Account: fees, rebates, telegraphic transfer promotion, document checklist, accounting links.
CIMB SME Account: fees, transactions, transfer promotion, SGD-MYR rate.
Airwallex Singapore pricing and Airwallex corporate cards: plans, FX, transfers, cards, integrations, licence.
Wise Business pricing (Singapore) and Wise Xero integration: fees, currencies, card, bank feeds.
Aspire pricing, Aspire corporate card and Aspire Xero integration: plans, FX, cards, regulatory disclosure, sync.
MAS Financial Institutions Directory: Airwallex (Singapore), Wise Asia-Pacific and Revolut Technologies Singapore as Major Payment Institutions.
MAS payment services licensing FAQ: e-money not covered by deposit insurance; safeguarding.
SDIC scope of coverage: who and what is insured.
ACRA: buying a Business Profile and free Business Profile download: cost and free copy.
Xero Singapore pricing and Xero price update: multi-currency on Premium, prices.
Want this handled properly? I do a free 20-minute systems review. No pitch, just your questions answered.
I'm Sayed. I work closely with business owners to automate their operations and build workflows that actually make sense. I write The Gantry about ERP and automation for SMEs.